Market overview and structural significance of the Low Borosilicate Glass Bottle Market
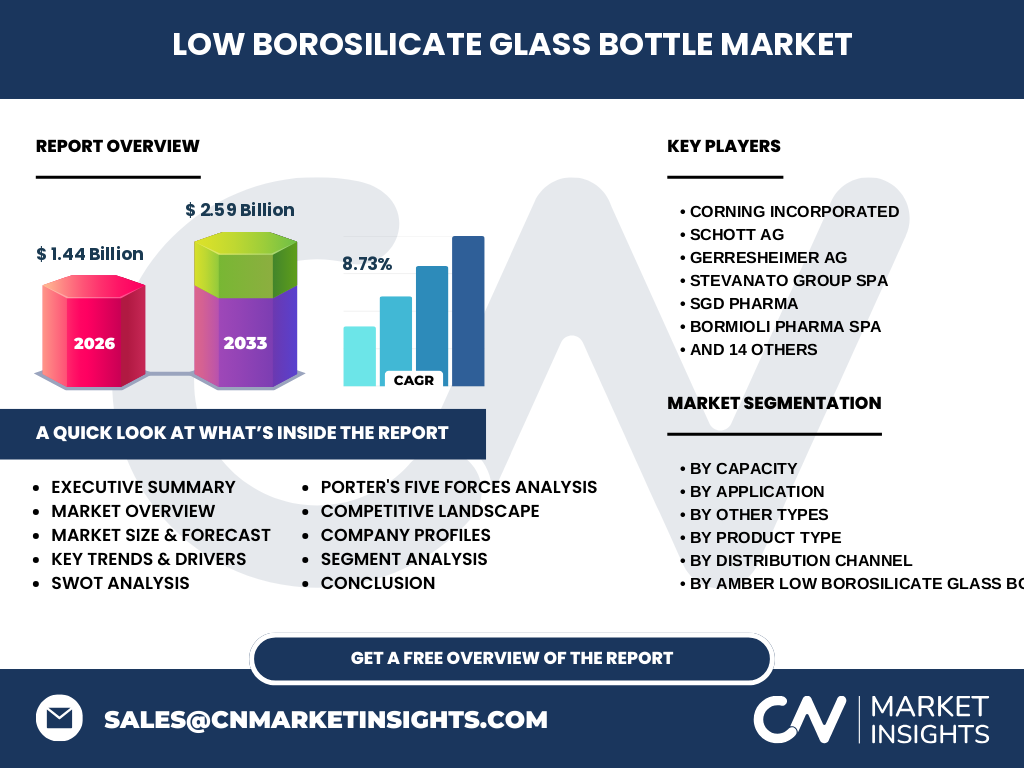
Our analysis indicates that the Low Borosilicate Glass Bottle Market represents a critical segment within pharmaceutical and industrial packaging. Valued at 1.44 Billion in 2026, the sector underpins supply chains requiring thermal shock resistance and chemical durability. Regulatory bodies like the USP and EP mandate stringent hydrolytic resistance, elevating specialized manufacturing standards.
Structural Growth Drivers and Market Restraints
The market is propelled by rising biologic formulations and strict pharmacopeia standards. Key restraints involve high furnace capital expenditures and raw material price volatility for silica sand and boric oxide. Logistical bottlenecks in cold-chain shipping further challenge regional distribution networks across major global ports.
The Shift Toward Advanced Packaging Trends
Industry trends reveal an accelerating migration toward Custom Color Low Borosilicate Glass Bottles and Frosted Low Borosilicate Glass Bottles in cosmetics. Manufacturers increasingly adopt ultra-clear formulations to enhance brand aesthetic while maintaining ultraviolet protection properties traditionally found in standard amber variants.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic severely disrupted supply chains and raw material procurement, yet catalyzed unprecedented demand for vaccine containment. Recovery trajectories show robust rebound mechanics, with automated fill-finish lines driving accelerated adoption of Small and Medium capacity vials globally.
Competitive Benchmarking and Industry Concentration
The competitive landscape features high consolidation among tier-one players like Corning Incorporated, SCHOTT AG, and Gerresheimer AG. These leaders leverage proprietary melting technologies to secure long-term pharma contracts, while regional players compete via aggressive B2B direct sales models.
Executive Summary of Key Findings
Executive insights confirm robust commercial health, projecting the market to reach 2.59 Billion by 2033 at an 8.73% CAGR. Strategic positioning in Green Low Borosilicate Glass Bottles and sustainable packaging offers primary avenues for margin expansion.
Market Forecast and Long-Term Projections from 2027 to 2033
Driven by emerging healthcare infrastructure across developing economies, our forecasts indicate steady expansion from 2027 to 2033. The market will scale from its baseline to reach 2.59 Billion, underpinned by a consistent 8.73% CAGR throughout the forecast window.
Segmentation Analysis across Capacity and Application
Segmentation is categorized by capacity (Small, Medium, Large) and application, covering Pharmaceuticals, Food And Beverages, and Cosmetics And Personal Care. Pharmaceuticals dominate volume demand due to injectable drug delivery needs, while cosmetics favor custom color variations.
Geographic Distribution and Regional Market Performance
Regional performance highlights heavy manufacturing concentrations in Asia-Pacific, supported by abundant raw material access. North America and Europe maintain steady demand driven by stringent FDA and EMA compliance frameworks governing pharmaceutical primary packaging.
In-Depth Regional Review of Manufacturing Hubs
Regional analysis points to intensive production clusters in regions housing key players like AGI glaspac and Hindusthan National Glass. Localized energy costs and strict environmental mandates directly influence regional output capacities and pricing strategies.
Strategic Positioning of Leading Companies
Industry giants such as Stevanato Group SpA, SGD Pharma, and Bormioli Pharma SpA focus on vertical integration and advanced coating technologies. Meanwhile, companies like Nipro Corporation and Kavalierglass AS target specialized laboratory and chemical end-use sectors.
Porter's Five Forces Assessment
Bargaining power of buyers remains moderate due to specialized regulatory qualifications required for pharmaceutical packaging. Threat of substitutes is low because borosilicate glass offers unmatched chemical inertness compared to standard plastics.
SWOT Analysis of the Industry Ecosystem
Strengths include superior thermal shock resistance and chemical stability. Weaknesses stem from high carbon emissions during glass melting. Opportunities lie in eco-friendly formulation recycling, while threats involve emerging polymer-based injectable alternatives.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with silica sand, boric oxide, and soda ash procurement. It progresses through high-temperature furnace melting, forming via automated I.S. machines, and culminates in distribution through Specialty Stores and B2B Direct Sales channels.
Investment Insights and High-Potential Areas
High-potential investment zones center on energy-efficient electric melting furnaces and automated optical inspection systems. Capital allocation toward Dark Amber Glass Bottles manufacturing yields resilient returns given pharma sector stability.
Conclusion and Strategic Takeaways
The market offers compelling growth, backed by a validated 8.73% CAGR toward 2.59 Billion by 2033. Stakeholders must prioritize sustainability compliance and technological upgrading to capture emerging pharmaceutical and cosmetic contracts.
Research Methodology and Baseline Triangulation
Our research methodology triangulates data by combining primary executive interviews with global trade registries, customs data, and secondary macroeconomic indicators. Baseline estimates for 2026 at 1.44 Billion are cross-verified with manufacturing capacity outputs.
Scope of the Report and Coverage Parameters
This report covers global production, consumption, and trade dynamics across key product types including Standard Clear Glass Bottles and Ultra-Clear Glass Bottles. Limitations exclude custom artisanal glassware outside industrial and commercial packaging parameters.
Recent Developments and Strategic Industry Moves
Recent market activities feature facility expansions by Vetropack Group and Verallia, alongside strategic partnerships focused on low-carbon glass production. Industry participants continue investing in advanced annealing tech to reduce defect rates in Standard Amber Glass Bottles.